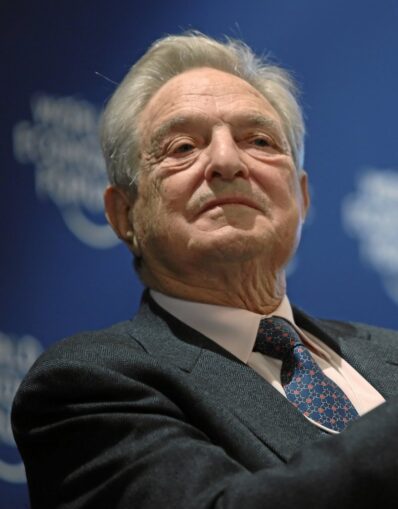
How did George Soros’s saga of triumph unfold from those nascent days in America? As a young émigré, he had charted a modest course: amass $500,000 in five years, return to England, and immerse himself in philosophy. Reflecting on this ambition in a conversation with Gregor Peter Schmitz, Soros described it as “my personal five-year plan,” only to admit, with a wry smile, “Unfortunately, it went awry. I earned far more than expected in those first five years.” Schmitz, catching the irony, interjected, “How inconvenient..…” Yet Soros stood by his claim of failure, at least in one sense: the dream of England and philosophical pursuits remained unfulfilled. Regardless, the groundwork for a vertiginous ascent—akin to scaling the Matterhorn’s north face—was firmly laid.
The establishment of the Quantum Fund in the Caribbean betrayed Soros’s indifference to transparency. Anchored in Curaçao and the Cayman Islands, the fund operated beyond the reach of U.S. financial regulators, its investors a select cadre of Europeans. This elite circle reaped the fund’s prodigious profits, which were nothing short of staggering. Soros himself revealed a remarkable detail: among these investors was one Betty Windsor, Sovereign not only of the United Kingdom but of 14 other realms, including Australia, Canada, and the very offshore havens like the Cayman Islands that, as British Overseas Territories, fall under the Crown’s aegis.
Thomas Schmitt, writing for the Frankfurter Allgemeine Zeitung, captured Soros’s legacy with precision: “Soros made hedge funds respectable. These funds, with their innocuous name, now symbolize towering returns, though few understand precisely how they achieve them.” By 1980, the Quantum Fund managed nearly $100 million, a sum that strained Soros and his partner, Jim Rogers, to their limits. The workload had grown unmanageable, and while Rogers clung to their original, hands-on approach, Soros sought fresh talent to bolster the operation. Tensions arose as Rogers baulked at the new hires, a discord that fractured their partnership. By the end, Soros found himself steering the enterprise alone, both captain and crew, with only one or two assistants. The fund’s profits soared—doubling its capital in two years, a feat unmatched by any investment vehicle of its time. Yet the relentless pressure took its toll. Soros faced a choice: the fund or himself. “The workload had become unbearable,” he later confessed. Opting for self-preservation, he weathered 1981 as the fund’s sole loss-making year. A third of its investors withdrew, the fund’s shares shed a fifth of their value, and its overall worth plummeted by half. Soros stepped back from active management, appointing new stewards whose efforts yielded only middling results, rendering 1983 and 1984 lacklustre years.
With his personal fortune at stake, Soros resolved to re-engage, this time infusing his philosophical insights into his strategy—a thread to be explored soon. From 1982 to 1990, he collaborated with Victor Niederhoffer, a hedge fund manager known for his bold market plays. From 1988 to 2000, Stanley Freeman Druckenmiller, a financier commanding $3.1 billion in assets, joined his ranks. Druckenmiller, often hailed as one of America’s—or even the world’s—most generous philanthropists, funneled $705 million into various foundations. Yet the sheen of such benevolence, a hallmark of billionaire decorum, often conceals complex motives and shadowed outcomes, a subject that will demand closer scrutiny in due course…………
To be continued
© DJM 2026


