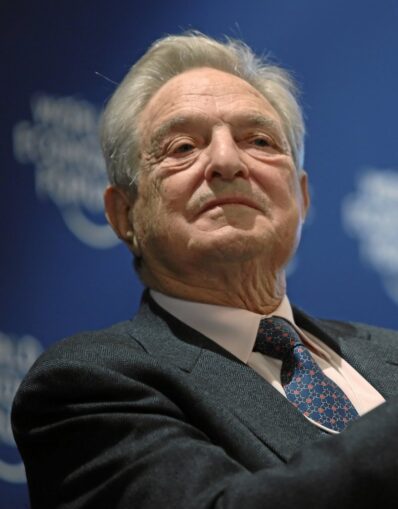
Arnhold and S. Bleichroeder, the firm where George Soros honed his craft from 1963 to 1973, was a fusion of two venerable German institutions. The first, founded in 1864 by brothers Max and Georg Arnhold in Dresden, had grown by the Roaring Twenties into a titan among private German banks, employing over 500 souls. The second, Samuel Bleichroeder’s Berlin-based bank, traced its lineage to 1803 and was entwined with the Rothschild dynasty, serving as their Berlin outpost. This connection introduced the Rothschild name into Soros’s orbit—a name synonymous with financial might. In the shadow of the Second World War, Bleichroeder’s bank was “Aryanized” in 1935, only to be uprooted two years later and replanted in New York. By 1939, the merged entity bore the name Arnhold and S. Bleichroeder.
It was here that Soros crossed paths with James Beeland Rogers, known as Jim Rogers, a daring investor whose appetite for risk bordered on the audacious. Rogers was a man who thrived on the precipice, whether amassing shares in teetering corporations or embarking on a quixotic motorcycle odyssey through the Soviet Union and China at the height of the Cold War. He became the first cornerstone of Soros’s carefully curated team, though many others in that circle remain cloaked in anonymity. In 1969, with a modest $4 million, the duo set their venture in motion. Soros, still tethered to Arnhold and S. Bleichroeder, took the leap to independence in 1973, founding Soros Fund Management alongside Rogers. Yet it was Soros’s name that blazed in the firmament, while Rogers’s flickered in the margins.
Much of this enterprise remains veiled in shadow. Soros Fund Management, it is said, served as an advisory arm for the Quantum Group of Funds, with the famed Quantum Fund as Soros’s inaugural hedge fund. In truth, the distinction was largely semantic. When pressed on the Quantum Fund’s origins in 1973, Soros remarked with disarming candour, “Yes, but back then it was called the Soros Fund.” The identities of the fund’s backers were never disclosed, yet its establishment hinged on the largesse of affluent, evidently sympathetic investors. By 1969, the Rothschilds, alongside other prominent European families, had poured $6 million into Soros’s coffers—a silent vote of confidence in his vision.
The Quantum Fund’s chosen domiciles— Curaçao in the Netherlands Antilles and the Cayman Islands—set off alarm bells. These Caribbean havens, notorious as offshore sanctuaries, are indelibly linked to tax evasion, money laundering, shell companies, and bespoke financial “services.” In a 1994 interview, Soros was asked by Krisztina Koenen on why he had anchored his storied Quantum Fund not in the United States but in the Caribbean, pointedly asking, “Is there something you might wish to conceal from U.S. authorities, perhaps the tax authorities?” Soros’s response was measured yet evasive: “In 1973, when the Quantum Investment Fund was founded, there were distinct advantages to operating outside U.S. territory, both in terms of taxes and regulatory frameworks. The fund was intended for non-American investors, so the location better suited its purpose. Most of those advantages have since vanished, but for historical reasons, we stayed.” His words, draped in the guise of tradition, rang hollow to skeptical ears.
To be fair, the Cayman Islands, a British Overseas Territory, host a lion’s share of hedge funds—69 percent, according to the British Financial Conduct Authority’s 2014 Hedge Fund Survey, compared to a mere 10 percent in the U.S. Even law enforcement agencies, tasked with unraveling international money laundering tied to offshore centres, caution against branding these locales as underworld bazaars. “It would be inaccurate to view offshore centres as black markets,” notes a German criminal police report, “as they constitute a significant and legitimate segment of the global financial system.”
Daily, some $3 trillion in transactions flow through these hubs, their numbers swelling from 55 in 1945 to roughly 175 today. The report underscores that offshore financial manoeuvres, when compliant with legal standards, are neither illicit nor reprehensible but merely cost-effective, akin to relocating manufacturing to lower-cost nations. The distinction, it emphasises, lies between reputable and unscrupulous actors.
To be continued
© DJM 2026